In This Article
- Medicare Is Changing in 2027
- PREMIUM ≠ COST
- Start With Your Doctors
- Then Look at the Medical Group
- Look at Hospital Costs
- Check Diagnostic Costs
- Know Your Maximum Out-of-Pocket
- Don’t Forget Your Drugs
- Look Beyond the Extras
- The Same Plan Can Change Every Year
- Medicare Is a Financial Decision Too
- Open the Hood Before You Buy the Car
- Education First. Enrollment Second.
If you are shopping for Medicare coverage for 2027, one number may grab your attention before all the others:
$0 premium.
It sounds wonderful.
And sometimes it is.
But a zero-dollar premium does not mean zero-dollar healthcare.
In fact, one of the biggest mistakes you can make when choosing a Medicare Advantage plan for 2027 is looking at the monthly premium first and everything else second.
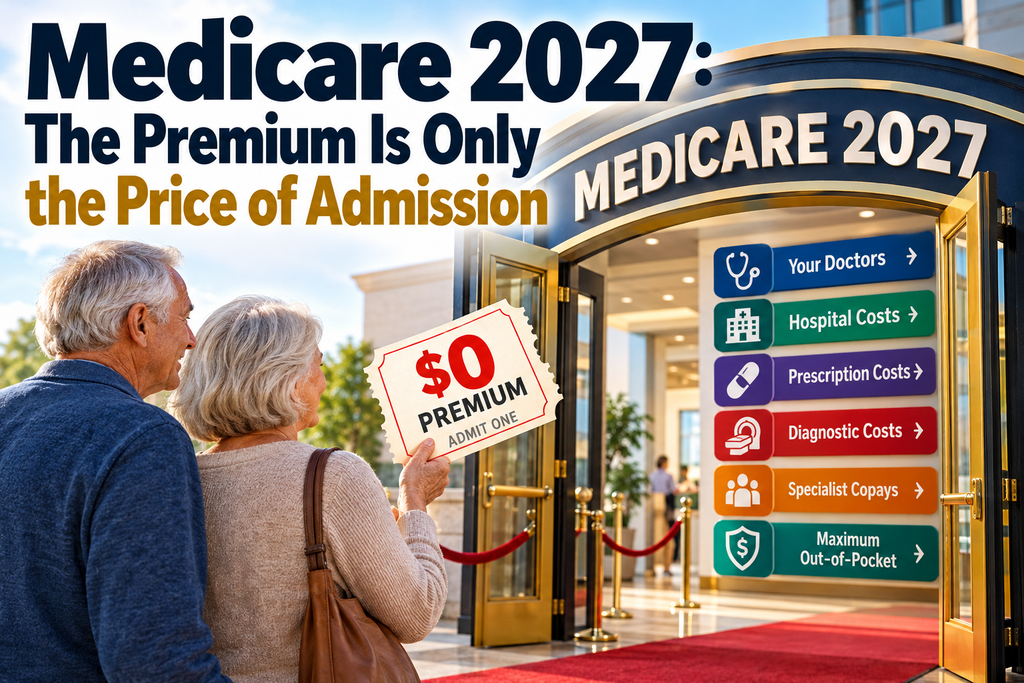
The premium is only the price of admission.
What happens after you walk through the door may matter much more.
Medicare Is Changing in 2027
Medicare beneficiaries have plenty of choices nationally for 2027.
CMS says more than 99% of Medicare beneficiaries will have access to at least one Medicare Advantage plan, and 97% will have access to ten or more choices. The weighted average Medicare Advantage premium is actually projected to decline from $14.37 in 2026 to about $12 in 2027.
That sounds reassuring.
But averages can hide what is happening in your ZIP code.
One county may have numerous zero-premium plans.
The neighboring county may have completely different choices.
A plan available last year may disappear.
A PPO may become an HMO.
Your doctor may no longer participate.
A specialist copayment may change.
Dental or over-the-counter benefits may change.
Your prescription costs may change.
And a plan carrying the same familiar insurance-company name may look considerably different in 2027 than it did in 2026.
That is why Medicare shopping needs to change.
PREMIUM ≠ COST
This may be the most important equation to remember during Medicare Annual Enrollment:
PREMIUM ≠ COST
Suppose Plan A has a $0 monthly premium.
Plan B costs $65 a month.
At first glance, Plan A appears to save you $780 a year.
Easy decision, right?
Not necessarily.
What if Plan A charges considerably more for hospital stays?
What if an MRI costs more?
What if your specialist costs more?
What if your doctor is outside the network?
What if your prescriptions fall into a different tier?
Suddenly that $780 premium savings doesn’t look quite as impressive.
This does not mean the $0 plan is bad.
It means you haven’t finished shopping.
Start With Your Doctors
For many people, especially those who already have an established relationship with physicians or specialists, the first question should be:
Are my doctors in the network?
Not:
What’s the premium?
And not:
How much do I get for dental?
Your primary care doctor, cardiologist, oncologist, orthopedist or other specialist may be far more important than an extra allowance on a benefits card.
This has become especially important as Medicare Advantage plans adjust their provider networks.
Even CMS recognizes the problem of keeping provider information accurate. On October 16, 2026, CMS proposed additional requirements intended to improve the accuracy of Medicare Advantage provider directories.
That’s an important development because anyone who has tried to verify a physician knows that provider directories aren’t always perfect.
So don’t stop with a logo beside a doctor’s name.
Verify.
Check the plan.
Check the medical group.
When necessary, call the doctor’s office.
And pay attention to the hospital system your doctor uses.
Then Look at the Medical Group
This is something many Medicare shoppers overlook.
You may think:
I only need to know if Dr. Smith takes the plan.
But Dr. Smith may belong to a larger medical group.
That group may determine what specialists, laboratories, imaging facilities and hospitals are easiest for you to use.
Medicare decisions increasingly aren’t just about one doctor.
They can be about an entire healthcare ecosystem.
Think of it this way.
You’re not simply choosing a doctor.
You’re choosing the roads that connect you to the rest of your medical care.
And discovering those roads are closed after you get sick is a lousy time to start reading the map.
Look at Hospital Costs
Hospitalization is where a Medicare Advantage plan can get expensive very quickly.
A plan may advertise a low premium but charge several hundred dollars per day for the first several days of an inpatient hospital stay.
Compare those numbers.
Don’t assume all plans work the same way.
Ask:
How much is an inpatient hospital stay?
How many days carry a copayment?
What happens if I need rehabilitation afterward?
What will outpatient surgery cost?
These aren’t exciting questions.
Neither is reading your homeowner’s insurance policy until the kitchen catches fire.
Some boring numbers become extremely interesting when you need them.
Check Diagnostic Costs
Another number people often miss is the cost of diagnostic testing.
Look specifically for:
MRI
CT scan
PET scan
X-rays
Outpatient diagnostic procedures
A plan may have attractive primary-care and specialist copayments while charging significantly more for advanced diagnostic testing.
For someone who rarely uses healthcare, that may not be particularly important.
For someone receiving ongoing treatment, it could matter considerably.
Medicare isn’t one-size-fits-all.
The best plan is not necessarily the plan with the biggest benefits.
It is the plan whose benefits best match the healthcare you actually use.
Know Your Maximum Out-of-Pocket
Every Medicare Advantage shopper should locate one number before enrolling:
The maximum out-of-pocket amount, or MOOP.
This is the limit on what you pay for covered Part A and Part B services within the plan’s rules during the year.
Think of it as your financial guardrail.
You may never come close to reaching it.
Hopefully you don’t.
But if you have a serious illness, accident, surgery or extended treatment, that number suddenly becomes very important.
Compare it between plans.
A $0 monthly premium may look attractive, but you should know the potential financial exposure sitting behind it.
And remember: prescription drug spending is governed separately under Part D rules and is not simply folded into the Medicare Advantage medical MOOP.
Don’t Forget Your Drugs
For 2027, Medicare Part D continues to provide an important financial protection for prescription drug costs.
CMS has codified the redesigned Part D benefit structure, including the elimination of the old coverage-gap phase and no cost sharing once an enrollee reaches the catastrophic phase.
But that does not mean every drug is covered the same way by every plan.
You still need to ask:
Is my medication on the formulary?
What tier is it?
Is there a deductible?
Does it require prior authorization?
Is my pharmacy preferred?
Would another pharmacy cost less?
Two people living next door to each other can have completely different Medicare needs simply because they take different medications.
That is why copying your neighbor’s Medicare plan is about as sensible as copying his eyeglass prescription.
It worked for him.
That doesn’t mean you’ll be able to see.
Look Beyond the Extras
Dental.
Vision.
Hearing.
Over-the-counter allowances.
Fitness programs.
Transportation.
These benefits can be valuable.
Use them.
Enjoy them.
But don’t allow an extra benefit to distract you from the fundamental purpose of health insurance.
Insurance exists to protect you when something goes wrong.
A few hundred dollars in extra benefits may not compensate for losing access to a physician you trust or facing thousands of dollars in additional medical expenses.
First shop the insurance.
Then shop the extras.
The Same Plan Can Change Every Year
One of the easiest Medicare decisions is:
I’ll just keep what I have.
Sometimes that’s exactly the right decision.
But it should be a decision.
Not an accident.
CMS itself encourages Medicare beneficiaries to review their coverage each year because plan costs and benefits can change from one year to the next.
Your Annual Notice of Change exists for a reason.
Open it.
Look at what changed.
Then compare.
You may discover that your existing plan remains your best choice.
Great.
Now you know.
Or you may discover something important before January instead of afterward.
That’s even better.
Medicare Is a Financial Decision Too
We tend to think of Medicare as a medical decision.
It isn’t only medical.
Medicare is also a financial decision.
The wrong combination of premiums, copayments, deductibles, prescriptions and network restrictions can potentially cost thousands of dollars.
That’s why the cheapest plan isn’t automatically the least expensive plan.
There is a difference.
Cheap is what you pay before you need healthcare.
Cost is what you pay after you use it.
Open the Hood Before You Buy the Car
Think about buying a car.
The paint is beautiful.
The seats are comfortable.
The salesperson shows you the entertainment system.
Wonderful.
But eventually somebody ought to open the hood.
Medicare is no different.
Before you enroll, open the hood.
Check:
Your doctors.
Your medical groups.
Your hospitals.
Your prescriptions.
Your specialist costs.
Your diagnostic costs.
Your inpatient hospital costs.
Your maximum out-of-pocket exposure.
Then look at the premium.
Now you’re comparing plans instead of advertisements.
Education First. Enrollment Second.
Medicare is changing.
The way you shop for Medicare should change also.
You don’t need somebody pushing you toward a plan.
You need good information.
You need the ability to compare.
And you need enough time to make a decision you understand.
That’s why our philosophy at MedicareSelfEnroll.com is simple:
Education first.
Enrollment second.
You can review Medicare choices, compare benefits and costs, check your prescriptions and explore your options from home.
If you find the right plan, you can enroll online.
There is no need to rush.
And there is no need to make your Medicare decision based on one attractive number printed in large type.
Because in 2027, perhaps the most important Medicare lesson is also the simplest:
Don’t shop the premium.
Shop the plan.
Visit MedicareSelfEnroll.com to compare your 2027 Medicare choices and make your decision with greater comfort, convenience and confidence.
We do not represent every plan available in your area. We represent most major Medicare plans in the areas we serve. You can also visit Medicare.gov or call 1-800-MEDICARE for information about all of your options.

William Vargas brings over 50 years of financial and insurance expertise to every Medicare conversation. He operates MedicareSelfEnroll.com, helping seniors in Florida, New York, and North Carolina — with no pressure, no phone calls required.