In This Article
- 1. Did Your Monthly Premium Change?
- 2. What Happened to Your Maximum Out-of-Pocket Limit?
- 3. Are Your Doctors Still in the Network?
- 4. Check Every Prescription Again
- 5. Look Beyond Dental, Vision and Grocery Benefits
- 6. Make Sure Your Plan Is Actually Returning for 2027
- 7. Compare Before You Automatically Renew
- Medicare Advantage or Medicare Supplement?
- You Don’t Have to Make a Decision Today
- AI Has Come to Medicare
- Education First. Enrollment Second.
- Your 2027 Medicare Checklist
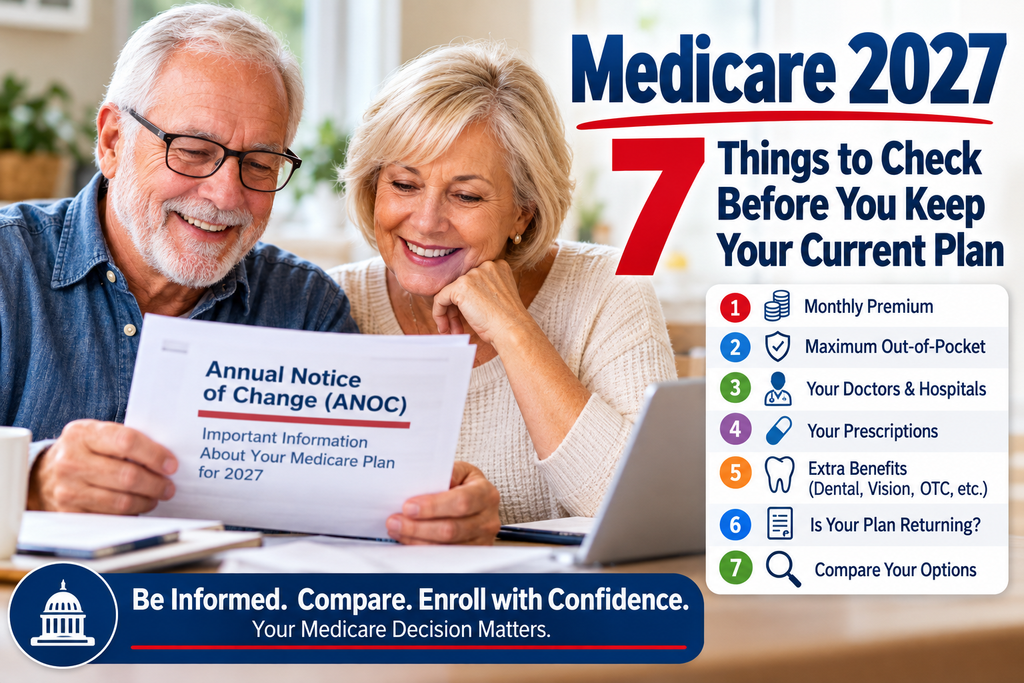
If you have Medicare, something important may be sitting in your mailbox right now.
It may not look very exciting. No flashing lights. No television celebrity. No giant red letters screaming, “PAY ATTENTION!”
It is your Annual Notice of Change, commonly called your ANOC.
And this year, you should read it.
Medicare plans can change from one year to the next. Your premium can change. Your copayments can change. Your prescriptions can change tiers. Your pharmacy can change status. Your doctors can leave the network. Extra benefits can shrink or disappear.
In some areas, an entire Medicare Advantage plan may no longer be available for 2027.
That does not mean you are losing Medicare.
It means it is time to look carefully at what you have and what your choices are for next year.
Medicare.gov says Medicare health and drug plans send members an Annual Notice of Change each fall explaining changes in coverage, costs and other plan details that take effect in January.
Here are seven things every Medicare beneficiary should check before automatically keeping the same plan for 2027.
1. Did Your Monthly Premium Change?
This is the obvious number, but don’t stop there.
Many people begin their Medicare comparison by asking:
“What is the premium?”
That’s understandable.
But a low premium does not necessarily mean low healthcare costs.
A Medicare Advantage plan may have a $0 or relatively low monthly plan premium while still requiring copayments or coinsurance when you use medical services.
Another plan might charge a monthly premium but offer different copayments, benefits or provider access.
That is why we frequently say at MedicareSelfEnroll.com:
PREMIUM ≠ COST.
Your premium is simply one piece of the puzzle.
Look at what you could actually pay if you need healthcare during the year.
2. What Happened to Your Maximum Out-of-Pocket Limit?
This may be one of the most overlooked numbers in Medicare Advantage.
Medicare Advantage plans generally have an annual maximum amount you can be required to pay for covered Part A and Part B services, subject to the plan’s rules.
Think of it as the financial guardrail around your medical expenses.
A person who rarely visits the doctor may barely notice this number.
Someone who has surgery, cancer treatment, frequent specialist visits, hospitalization or other significant medical care may care about it very much.
When comparing your 2026 coverage with your 2027 coverage, don’t simply ask:
“Did my premium go up?”
Ask:
“How much financial exposure do I have if I become seriously ill?”
Those are two very different questions.
Medicare is not simply a medical decision.
Medicare is also a financial decision.
3. Are Your Doctors Still in the Network?
This is a big one.
Never assume that because your doctor accepted your Medicare Advantage plan in 2026, the situation will automatically be identical in 2027.
Provider networks can change.
Check your:
- Primary care physician
- Cardiologist
- Oncologist
- Orthopedist
- Dermatologist
- Urologist
- Hospital
- Rehabilitation facility
- Other specialists you regularly use
And don’t rely entirely on what happened last year.
Verify your providers for the new plan year.
For Medicare Advantage members, network rules can have a significant effect on both access and cost.
This is particularly important for people who travel frequently, spend part of the year in another state, or want broader access to physicians.
An HMO and a PPO are not the same thing.
Understand what you’re buying before January arrives.
4. Check Every Prescription Again
This is where many Medicare beneficiaries can get surprised.
A prescription that was covered favorably this year may be treated differently next year.
Your drug could:
- Move to another tier
- Require prior authorization
- Have quantity limits
- Require step therapy
- Cost more
- Cost less
- No longer be on the same formulary
Your pharmacy matters too.
A pharmacy that gave you favorable pricing in 2026 may not have the same status under your 2027 plan.
This is why Medicare drug coverage should be compared using your actual prescriptions, not somebody else’s.
Your neighbor’s Medicare plan could be wonderful for your neighbor and terrible for you.
Medicare Part D continues to undergo significant changes. CMS announced additional 2027 Part D information in July 2026 as insurers finalized their offerings for the coming year.
Always check current plan documents and Medicare.gov before making your final decision.
5. Look Beyond Dental, Vision and Grocery Benefits
Extra benefits are popular.
And there is nothing wrong with that.
Dental coverage can be valuable. So can hearing, vision, transportation, fitness programs, OTC allowances and other supplemental benefits.
But don’t allow a shiny extra benefit to distract you from the basic healthcare coverage underneath it.
Suppose one plan gives you a larger OTC allowance but your preferred hospital isn’t in the network.
Which is more important?
Suppose another plan offers attractive dental benefits but your specialist copayment increased substantially.
Which matters more?
There isn’t one answer for everybody.
That’s exactly the point.
Your Medicare plan should fit your situation.
Look at the core medical coverage first.
Then evaluate the extras.
The free toothbrush shouldn’t be driving the bus.
6. Make Sure Your Plan Is Actually Returning for 2027
This year this question deserves particular attention.
Medicare Advantage insurers make business decisions every year about where they will offer plans and what those plans will include.
CMS finalized its 2027 Medicare Advantage and Part D payment policies in April 2026. CMS projected an average 2.48% increase—more than $13 billion—in Medicare Advantage payments for 2027, although what an individual beneficiary experiences depends on the specific plan available where that person lives.
An increase in overall Medicare Advantage payments does not guarantee that your particular plan will remain unchanged.
Insurers can still alter individual offerings, premiums, benefits, networks and service areas.
That’s why your ANOC and any non-renewal notice deserve your attention.
If your plan is leaving your area, don’t panic.
You aren’t losing Medicare.
But you may need to select another Medicare option.
And certain circumstances involving plan termination or loss of coverage can create special enrollment or Medigap rights, depending on the situation.
Read any official notice carefully before making a move.
7. Compare Before You Automatically Renew
Human beings like familiarity.
If something worked yesterday, our natural tendency is to keep doing it tomorrow.
Medicare doesn’t always reward that approach.
A plan that was a very good choice three years ago isn’t automatically a very good choice today.
Your health may have changed.
Your medications may have changed.
Your doctors may have changed.
Your finances may have changed.
And the plan itself may have changed.
So compare.
Not because you necessarily need to switch.
You may discover that your existing plan is still perfectly suitable for you.
But keeping a plan after comparing it is very different from keeping a plan simply because you didn’t look.
Medicare Advantage or Medicare Supplement?
For many people, the larger Medicare decision eventually comes down to what we call:
The Medicare Fork in the Road
Do you want Medicare Advantage?
Or do you want Original Medicare combined with Medicare Supplement insurance and typically separate Part D drug coverage?
Neither system is automatically right for everyone.
Medicare Advantage may offer lower monthly premiums and additional benefits, but it generally involves a managed-care structure and plan-specific networks, copayments and rules.
Medicare Supplement insurance generally provides broader access to providers who accept Medicare and helps cover certain Original Medicare cost-sharing, but it requires an additional premium. Prescription drug coverage normally must be purchased separately.
There can also be important rules concerning when you can purchase a Medigap policy without medical underwriting.
That makes this much bigger than:
“Which plan has the lowest premium?”
You’re choosing how you want to receive your Medicare coverage.
Take that decision seriously.
You Don’t Have to Make a Decision Today
There is an enormous amount of Medicare advertising during enrollment season.
Your mailbox fills up.
Your television starts shouting at you.
The phone calls begin.
Someone always seems to be telling you that you need to “CALL NOW!”
You don’t.
Take your time.
Learn.
Compare.
Ask questions.
Your objective isn’t to make the fastest Medicare decision.
Your objective is to make an informed Medicare decision.
AI Has Come to Medicare
There’s another major change taking place that has nothing to do with Medicare legislation.
Artificial intelligence is changing how consumers can educate themselves.
You can now use AI to help you understand terminology in your ANOC.
You can ask:
“What does coinsurance mean?”
“What is a drug formulary?”
“What is the difference between an HMO and a PPO?”
“What does maximum out-of-pocket mean?”
“What questions should I ask before changing Medicare plans?”
AI can be a powerful educational tool.
But remember something important:
AI can be wrong.
Never enter your Medicare number, Social Security number, banking information or other sensitive personal information into a general-purpose AI chatbot.
Use AI to become better informed, then verify important coverage information through official sources such as Medicare.gov, your insurance company and plan documents.
Education First. Enrollment Second.
At MedicareSelfEnroll.com, we believe Medicare doesn’t have to begin with a sales call.
You should be able to learn first.
Ask questions.
Compare your choices.
Take your time.
And when you’re comfortable, enroll.
You don’t need someone calling you five minutes after you ask a Medicare question.
You don’t need pressure.
And you shouldn’t have to provide personal information just to learn how Medicare works.
That’s why our philosophy is simple:
Education first. Enrollment second.
The Medicare enrollment process is changing right before our very eyes.
Consumers have more information, more technology and more ability to participate in their own decisions than ever before.
Use it.
Your 2027 Medicare Checklist
Before deciding whether to keep your plan, check these seven things:
- Your monthly premium.
- Your maximum out-of-pocket exposure.
- Your doctors and hospitals.
- Your prescription drugs and pharmacies.
- Your major copayments and benefits.
- Whether your plan is returning for 2027.
- Your alternatives before automatically renewing.
Then ask yourself one final question:
“If I were choosing Medicare today, knowing what I know now, would I still choose this plan?”
That’s a much better question than:
“Should I just keep what I have?”
Ready to Explore Your Choices?
Visit MedicareSelfEnroll.com.
Learn about Medicare.
Compare available plans.
Ask questions.
Take your time.
And when you’re ready, enroll with confidence.
No rush. No pressure.
Because an informed senior makes better choices.
MedicareSelfEnroll.com does not represent every plan available in your area. Currently, we represent selected organizations that offer Medicare products. For information about all of your Medicare options, contact Medicare.gov, call 1-800-MEDICARE, or contact your State Health Insurance Assistance Program (SHIP). Plan availability, benefits, premiums, networks, formularies and costs vary by location and may change each year.

William Vargas brings over 50 years of financial and insurance expertise to every Medicare conversation. He operates MedicareSelfEnroll.com, helping seniors in Florida, New York, and North Carolina — with no pressure, no phone calls required.