In This Article
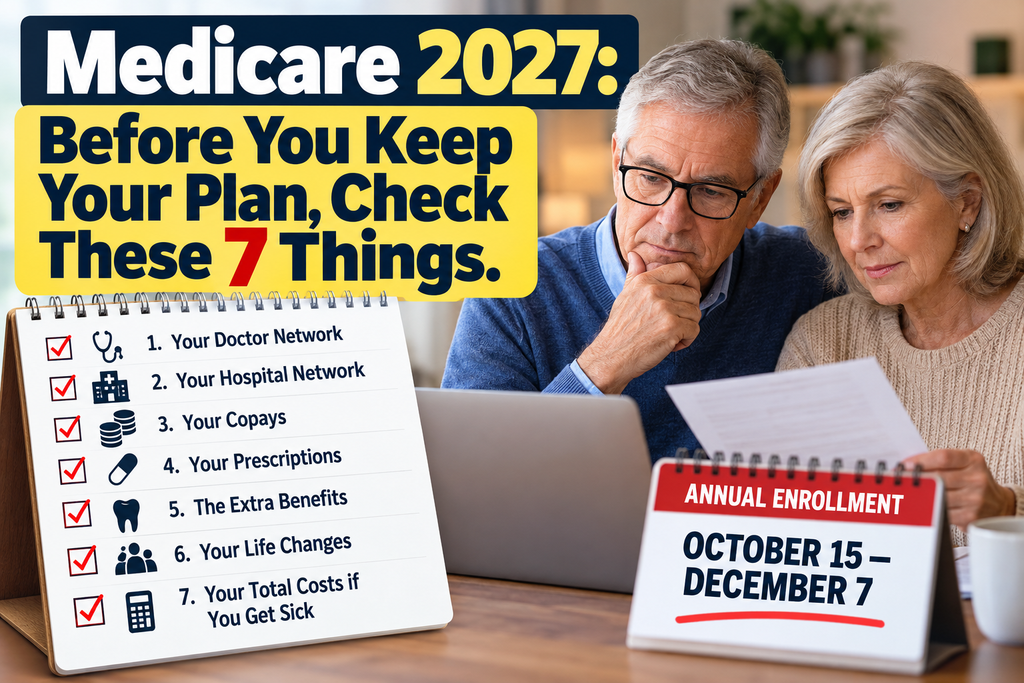
Every fall, millions of people with Medicare face the same question:
Should I keep my current Medicare plan for another year?
For many people, the easiest answer is:
“It worked this year. I’ll just keep it.”
That may turn out to be the right decision.
But for 2027, don’t make that decision until you look under the hood.
Your Medicare Advantage plan can keep the same name and still change important details.
Your premium can change.
Your doctor network can change.
Your hospital can change.
Your prescription costs can change.
Copayments can change.
Dental, vision, hearing and over-the-counter benefits can change.
And in some areas, a plan may no longer be offered at all.
That is why our message at MedicareSelfEnroll.com is simple:
Education first. Enrollment second.
Before you keep your Medicare plan for 2027, check these seven things.
1. IS YOUR DOCTOR STILL IN THE NETWORK?
Start here.
Not with the premium.
Not with the dental allowance.
Not with the television commercial.
Start with your doctors.
If you have a Medicare Advantage plan, particularly an HMO or PPO, provider networks matter.
Ask yourself:
Is my primary care doctor still participating?
Are my specialists participating?
What about my cardiologist?
Orthopedist?
Oncologist?
Endocrinologist?
Eye doctor?
The doctor who treats a chronic condition may be far more important to you than an extra benefit advertised on television.
And don’t assume that because your doctor accepted your plan in 2026, the doctor will automatically accept it in 2027.
Networks can change.
That’s why we recommend checking each important provider individually.
Also pay attention to whether the provider is simply listed in the directory or actually accepting patients under that particular Medicare Advantage plan.
Those are not always the same thing.
A good rule:
Check the doctor before you check the extras.
2. IS YOUR HOSPITAL STILL INCLUDED?
This gets overlooked surprisingly often.
People carefully check their primary care physician and then forget about the hospital.
Suppose your doctor is in the plan but the hospital system you normally use isn’t.
That can become a much bigger issue than saving a few dollars per month.
Consider the hospitals you would realistically use.
Which hospital would an ambulance take you to?
Where does your surgeon operate?
Where does your cardiologist practice?
Where would you want to receive cancer treatment or rehabilitation?
If you live near a county line, look beyond your own county.
Many seniors routinely receive medical care in a neighboring county.
Your Medicare plan should fit the way you actually obtain healthcare, not simply the ZIP code where you sleep at night.
3. WHAT HAPPENED TO YOUR COPAYS?
This is where people can get fooled by premiums.
Imagine two Medicare Advantage plans.
Plan A costs $0 per month.
Plan B costs $50 per month.
At first glance, Plan A looks cheaper.
But what if Plan A charges considerably more for specialists, diagnostic testing, outpatient surgery or hospital stays?
Which plan is really cheaper?
You can’t answer that question by looking at the premium alone.
Review:
Primary care copays.
Specialist copays.
Emergency room costs.
Urgent care.
Diagnostic imaging.
Outpatient surgery.
Physical therapy.
Hospital costs.
Skilled nursing benefits.
And your maximum out-of-pocket limit.
That last number deserves particular attention.
PREMIUM DOES NOT EQUAL COST.
A low-premium plan can still become an expensive plan if you require substantial healthcare during the year.
Medicare is not simply an insurance premium decision.
It is a potential annual healthcare cost decision.
4. CHECK YOUR PRESCRIPTIONS AGAIN
Your medications didn’t necessarily change.
But your plan’s coverage of them may have.
Prescription drug formularies can change from year to year.
A medication may move to another tier.
Your copayment may change.
Prior authorization may be required.
Quantity limits may change.
Your preferred pharmacy may change.
Another pharmacy may suddenly become less expensive.
That is why entering your actual medications into a Medicare comparison tool can be so important.
Don’t compare prescription coverage based on what happened last year.
Compare what those prescriptions are expected to cost in 2027.
CMS says plan costs and benefits can change annually and encourages beneficiaries to review their existing coverage and compare their options during Annual Enrollment.
For people taking several medications, this comparison can make a substantial difference.
5. DON’T LET THE EXTRAS MAKE THE DECISION FOR YOU
Dental.
Vision.
Hearing.
Over-the-counter allowances.
Gym memberships.
Transportation.
Food benefits.
These benefits can be valuable.
There is nothing wrong with wanting them.
But put them in the correct order.
Your medical care comes first.
Imagine choosing a plan because it gives you an attractive dental benefit…
only to discover that your cardiologist isn’t in the network.
That’s not much of a bargain.
The extras should help you choose between otherwise appropriate plans.
They should not convince you to choose a medical plan that doesn’t meet your healthcare needs.
Think of buying a car.
The heated seats are nice.
But first we might want to make sure the engine works.
6. HAS YOUR LIFE CHANGED?
Sometimes the Medicare plan hasn’t changed very much.
You have.
Maybe you received a new diagnosis.
Maybe you now see specialists you didn’t see last year.
Maybe you started expensive medications.
Maybe you’re planning surgery.
Perhaps you are spending several months each year in Florida.
Maybe you’re traveling more.
Maybe you’ve moved.
Maybe you simply want more freedom to see providers outside a local network.
Your Medicare coverage should reflect your life today.
Not the life you had three years ago when you originally selected the plan.
This is especially important when comparing an HMO with a PPO.
An HMO may work beautifully for someone who receives virtually all care within a strong local network.
Someone who travels frequently or receives care in several locations may place greater value on the flexibility of a PPO.
Neither is automatically better.
The question is:
Which structure fits you?
7. WHAT IS YOUR PLAN REALLY GOING TO COST IF YOU GET SICK?
This may be the most important question of all.
It’s easy to compare Medicare plans when you’re healthy.
The real test is what happens when something goes wrong.
Suppose next year you need:
A hospital stay.
An MRI.
Physical therapy.
Specialist visits.
Outpatient surgery.
Radiation.
Chemotherapy.
A series of injections.
Rehabilitation.
What would your share of those costs be?
That is why you should know the plan’s maximum out-of-pocket amount.
The maximum out-of-pocket limit does not mean you will spend that amount.
Many people never come close.
But it tells you something about your financial exposure if you experience a serious medical year.
And remember that prescription drug spending is generally separate from the Medicare Advantage medical maximum out-of-pocket calculation.
When evaluating a plan, don’t only ask:
“What does this plan cost when I’m healthy?”
Also ask:
“What could this plan cost me if I’m sick?”
That is a much better question.
WHAT IS CHANGING NATIONALLY FOR 2027?
CMS says the Medicare Advantage market remains broadly available for 2027.
More than 99% of Medicare beneficiaries are expected to have access to at least one Medicare Advantage plan, and CMS projects that 97% will have access to ten or more Medicare Advantage choices.
CMS also projects the weighted average Medicare Advantage premium nationally to decrease from $14.37 in 2026 to approximately $12 in 2027.
Those national numbers sound encouraging.
But here’s the problem:
You don’t enroll in a national average.
You enroll in a particular plan.
In a particular county.
With a particular network.
With your doctors.
Your hospitals.
Your medications.
And your medical needs.
A national statistic cannot tell you whether your cardiologist is participating in your plan.
That’s why individual comparison matters.
ANNUAL ENROLLMENT BEGINS OCTOBER 15
The Medicare Annual Enrollment Period runs from:
October 15 through December 7, 2026.
Coverage changes made during this period generally become effective January 1, 2027.
CMS specifically encourages Medicare beneficiaries to use Annual Enrollment to review their current coverage because plan costs and benefits can change from one year to the next.
But there is no prize for enrolling on October 15.
And there is no advantage to waiting until December 7 at 11:45 at night either.
Take your time.
Learn.
Ask questions.
Compare.
Then decide.
YOU MAY NOT NEED TO CHANGE ANYTHING
This is important.
Annual Enrollment does not mean you should change your Medicare plan.
Sometimes the best Medicare decision you can make is:
Do nothing.
If your doctors remain in network…
your hospitals are included…
your medications are covered appropriately…
the costs remain reasonable…
and the plan still fits your healthcare needs…
keeping your existing plan may make perfect sense.
The purpose of Annual Enrollment isn’t to change plans.
The purpose is to make sure the plan you have still works for you.
A BETTER WAY TO SHOP FOR MEDICARE
For years, Medicare shopping often started with a salesperson.
We think it should start with information.
At MedicareSelfEnroll.com, you can educate yourself before making a decision.
Learn how Medicare works.
Ask questions.
Compare your choices.
Take your time.
And when you’re comfortable, you can enroll yourself online.
No pressure.
You don’t need someone calling you repeatedly.
You don’t need another television commercial.
And you don’t have to make a decision because somebody told you a particular plan was “the best.”
There is no single best Medicare plan for everybody.
There is only the plan that best fits your circumstances.
Your doctors.
Your hospitals.
Your prescriptions.
Your budget.
Your health.
Your lifestyle.
BEFORE YOU CLICK “ENROLL”
Ask yourself seven questions:
- Are my doctors participating?
- Are my hospitals participating?
- What changed in my copayments?
- Are my prescriptions still covered affordably?
- Am I choosing healthcare coverage or being distracted by extra benefits?
- Does this plan fit the way I live today?
- What could this plan cost me during a bad medical year?
If you can answer those seven questions, you’re already approaching Medicare differently.
And that’s exactly the point.
Medicare is changing.
The way you shop for Medicare should change also.
Before you enroll:
Educate yourself first.
Learn.
Ask.
Compare.
Decide.
Then enroll with confidence at MedicareSelfEnroll.com.
Medicare Disclosure
We do not offer every plan available in your area. Currently, we represent multiple organizations that offer Medicare Advantage products in the areas we serve. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
MedicareSelfEnroll.com is not connected with or endorsed by the U.S. government or the federal Medicare program.

William Vargas brings over 50 years of financial and insurance expertise to every Medicare conversation. He operates MedicareSelfEnroll.com, helping seniors in Florida, New York, and North Carolina — with no pressure, no phone calls required.