In This Article
- Your Premium Is Only One Number
- PREMIUM DOES NOT EQUAL COST.
- Medicare Is Local
- Start With Your Doctors
- Look Under the Hood
- Your Plan Does Not Have to Disappear to Change
- The Average Doesn’t Matter When You Are the Patient
- Don’t Shop for Medicare Backwards
- Medicare Is a Financial Decision Too
- You Have More Information Than Ever Before
- Education First. Enrollment Second.
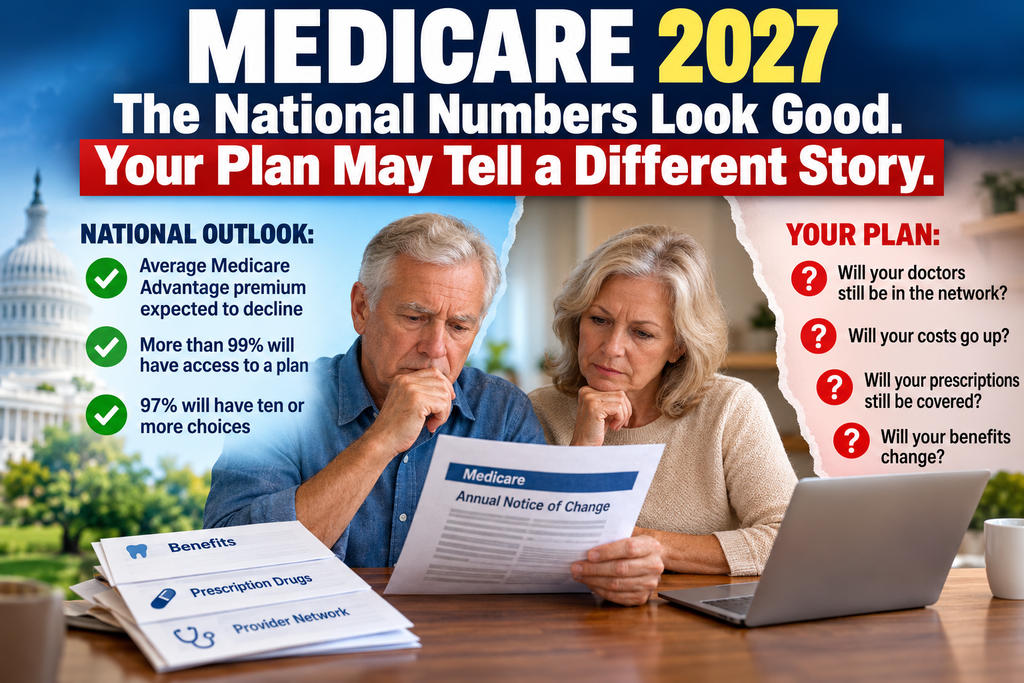
If you have been watching the news about Medicare for 2027, you may be wondering what all the concern is about.
After all, the Centers for Medicare & Medicaid Services says the Medicare Advantage market remains broadly stable.
CMS projects the average Medicare Advantage premium will actually decline in 2027, from $14.37 a month in 2026 to about $12. CMS also says more than 99% of Medicare beneficiaries will have access to at least one Medicare Advantage plan, and 97% will have access to ten or more choices.
That sounds reassuring.
But there is another side to the story.
National averages do not tell you what is happening to YOUR Medicare plan.
And that may be the most important lesson of Medicare 2027.
Your Premium Is Only One Number
For years, Medicare advertising has trained people to look at one number first:
$0 PREMIUM
It certainly gets your attention.
But a Medicare plan is not a television price tag.
A zero dollar premium does not necessarily mean a zero dollar cost.
You still need to look at:
- Your doctors
- Your hospitals
- Specialist copays
- Hospital copays
- Prescription drug costs
- Maximum out of pocket exposure
- Dental coverage
- Hearing coverage
- Vision benefits
- Over the counter benefits
- Prior authorization requirements
- Network restrictions
A plan could keep the same premium and become considerably more expensive for you if the other numbers change.
That is why I keep saying:
PREMIUM DOES NOT EQUAL COST.
For 2027, that distinction is especially important.
Medicare Is Local
CMS can tell us what is happening across the United States.
But Medicare Advantage is still very much a local product.
A plan available in one county may not be available in the county next door.
A plan can remain available but change its provider network.
A hospital may participate while a particular medical group does not.
A PPO may disappear and be replaced by an HMO.
A plan that works beautifully for your neighbor might be completely wrong for you.
That is why statements such as:
“This is the best Medicare plan.”
should immediately make you suspicious.
The better question is:
“Is this the right Medicare plan for me?”
Those are two entirely different questions.
Start With Your Doctors
Before you become impressed by dental allowances, gym memberships, grocery cards or television commercials, check the people who actually take care of you.
Your primary care doctor.
Your cardiologist.
Your orthopedic doctor.
Your oncologist.
Your medical group.
And the hospital you would want to use if something serious happened.
A Medicare Advantage plan with attractive benefits does you very little good if the doctors you depend upon are outside its network.
This has become one of the biggest issues I am seeing while reviewing 2027 plans.
And simply seeing the word PPO does not solve the problem.
PPO plans generally offer some out of network coverage, but that does not mean every doctor must accept the plan. Your cost sharing may also be substantially higher outside the network.
Check.
Then check again.
Look Under the Hood
Think of your Medicare plan like a car.
The paint can still be shiny.
The seats can still look great.
The salesman can still tell you how wonderful it is.
But before taking it on a long trip, you might want to open the hood.
Your Medicare Annual Notice of Change is your chance to do exactly that.
Look for changes in:
Specialist costs
A small change here may not seem important until you see several specialists throughout the year.
Hospital costs
Ask yourself what happens financially if you are hospitalized for three, five or seven days.
Maximum out of pocket
This may be one of the most overlooked numbers in Medicare Advantage.
If you have a serious illness, this number can suddenly become very important.
Prescription drugs
Make sure your drugs are still covered.
Then check their tiers.
Then check the deductible.
Then check your pharmacy.
The Part D benefit itself continues to provide stronger catastrophic protection than Medicare beneficiaries had only a few years ago. CMS has incorporated the redesigned Part D structure into the rules for 2027 and beyond, including eliminating beneficiary cost sharing in the catastrophic phase.
But formularies and individual plan costs still matter.
Extra benefits
Dental.
Vision.
Hearing.
Over the counter allowances.
Transportation.
Fitness.
These are valuable benefits.
But don’t allow a benefit worth a few hundred dollars to distract you from a healthcare expense that could cost thousands.
Your Plan Does Not Have to Disappear to Change
This is another important point.
Many people assume:
“I haven’t received a cancellation notice, so I’m fine.”
Not necessarily.
Your plan may remain in existence while changing:
- Copays
- Coinsurance
- Drug coverage
- Networks
- Dental benefits
- OTC benefits
- Givebacks
- Referral requirements
- Prior authorization rules
CMS itself encourages beneficiaries to review their coverage because plan costs and benefits can change from one year to another.
That is not fine print.
That is good advice.
The Average Doesn’t Matter When You Are the Patient
Imagine somebody telling you:
“The average temperature in America today is 58 degrees.”
Interesting.
But should you wear a winter coat?
That depends on where YOU live.
Medicare works much the same way.
CMS says approximately eight out of ten Medicare Advantage beneficiaries should be able to remain in their current plan with the same or a lower premium in 2027.
Good news.
But are you one of the eight?
And even if your premium stays the same, did everything else stay the same?
Those are the questions that matter.
Don’t Shop for Medicare Backwards
Many people shop this way:
What benefits does the plan give me?
I suggest reversing the process.
Start here:
What do I need?
Write down:
- My doctors
- My hospitals
- My prescriptions
- My preferred pharmacies
- My expected medical needs
- My travel needs
- My budget
Now compare plans against your list.
That turns Medicare shopping from a sales presentation into a decision making process.
And that is exactly what it should be.
Medicare Is a Financial Decision Too
People understandably think of Medicare as health insurance.
It is.
But choosing Medicare coverage is also a financial decision.
Suppose one plan costs $0 a month and another costs $65.
The zero premium plan sounds cheaper.
But what happens if the $65 plan gives you access to your doctors and the $0 plan does not?
What happens if one plan has substantially lower hospitalization costs?
What happens if one plan covers your expensive medication differently?
Suddenly the cheapest premium may not produce the lowest total cost.
This is why Medicare cannot be reduced to one number.
You Have More Information Than Ever Before
There is some genuinely good news for Medicare beneficiaries.
The tools for comparing plans continue to improve.
CMS says Medicare.gov now makes it easier to save providers, compare plans, review plan documents and see information about changes affecting current coverage.
That is a major step in the right direction.
For decades, Medicare shopping depended heavily on someone sitting across the kitchen table explaining what they wanted you to buy.
That world is changing.
Today you can sit at your computer, tablet or phone and compare your options yourself.
You can look at benefits.
You can check prescriptions.
You can compare costs.
You can investigate provider networks.
And when something doesn’t make sense, you can ask questions before making a decision.
That is what I call:
SELF SERVICE MEDICARE.
Education First. Enrollment Second.
You should never feel pressured to make a Medicare decision.
And you certainly should not choose a plan simply because somebody called you, mailed you a brochure or showed you a television commercial.
Take your time.
Ask questions.
Compare.
Verify.
Then decide.
At MedicareSelfEnroll.com, you can enter your ZIP code, compare available Medicare plans, review benefits and costs, check prescriptions and, when you are ready, enroll online.
There is no need for someone to chase you around the house with a telephone.
No pressure.
No obligation.
Just information.
Because Medicare is changing.
And the way we shop for Medicare should change too.
Education first. Enrollment second.
Visit MedicareSelfEnroll.com and take a look at what Medicare 2027 actually looks like where YOU live.
Because when it comes to Medicare, the national average is interesting.
Your plan is what matters.

William Vargas brings over 50 years of financial and insurance expertise to every Medicare conversation. He operates MedicareSelfEnroll.com, helping seniors in Florida, New York, and North Carolina — with no pressure, no phone calls required.