In This Article
- Medicare Advantage Plans Are Under Pressure
- Your $0 Premium Plan May Still Exist — But What Is Inside It?
- Part D Is Becoming One of the Biggest 2027 Stories
- Do Not Confuse the $2,400 Drug Cap With Your Total Medicare Costs
- Your Doctor May Matter More Than Your Premium
- Star Ratings Are Changing Too
- Medicare 2027 Is Becoming More About Risk
- What Should You Do When Your 2027 ANOC Arrives?
- October 15 Is When the Real Shopping Begins
- The 2027 Medicare Marketplace Is Still Taking Shape
- The Bottom Line for Medicare 2027
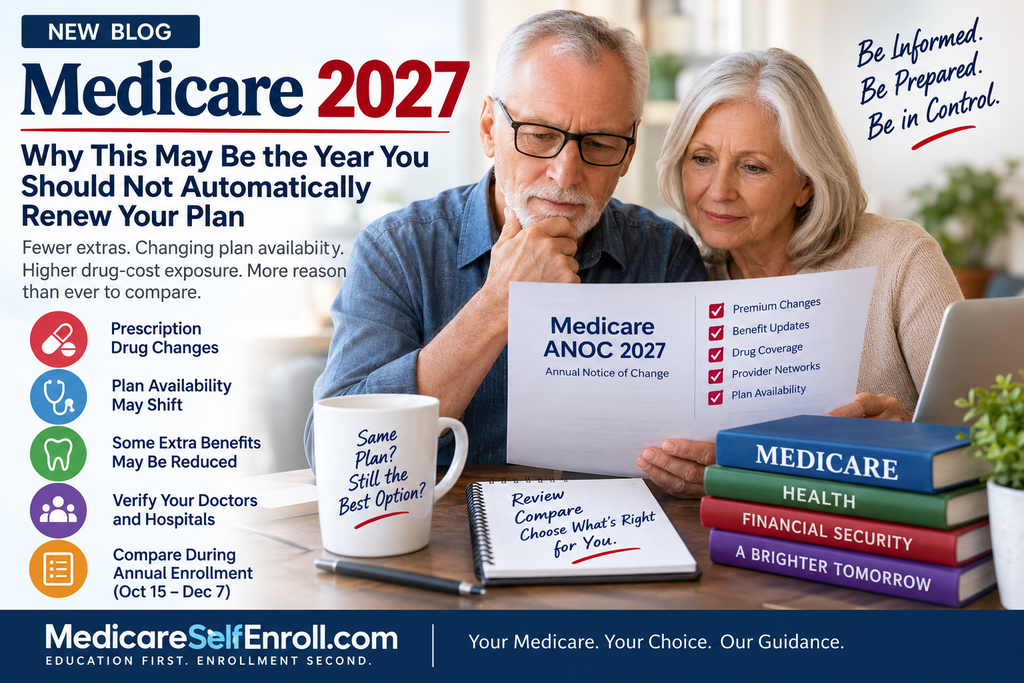
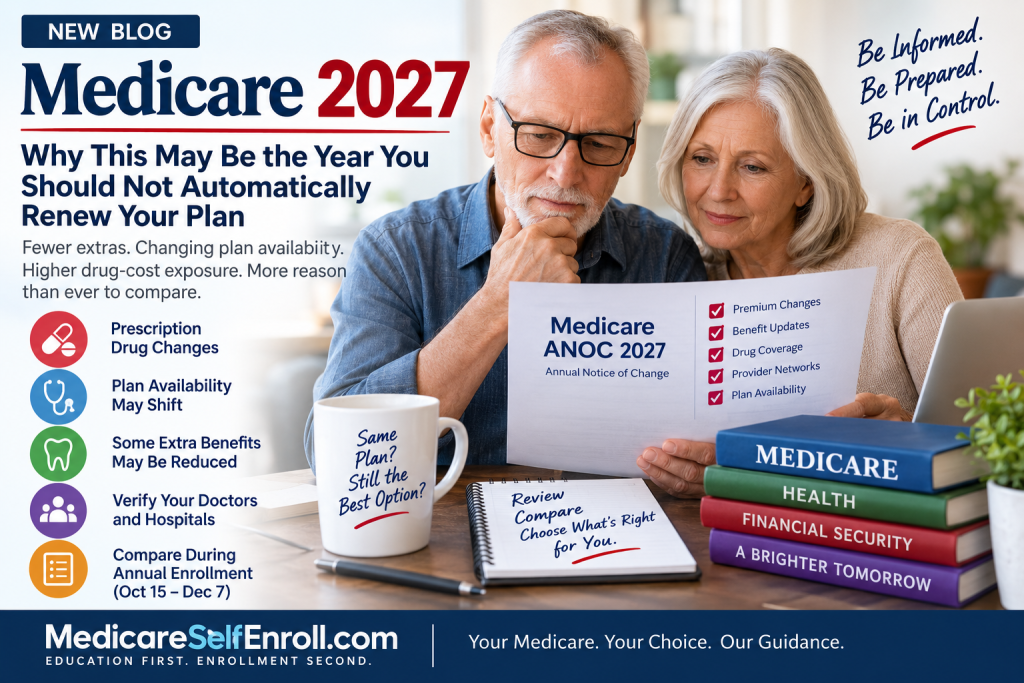
For years, many people on Medicare have treated annual enrollment almost like renewing a magazine subscription.
The plan worked last year.
The premium still looks reasonable.
The insurance company sends a notice saying the plan is continuing.
So you keep it.
For 2027, that could be a mistake.
The Medicare marketplace is entering a period of significant change, particularly in Medicare Advantage and Part D prescription drug coverage. Insurers are adjusting benefits, reevaluating which counties they want to serve, managing higher medical costs, and preparing for changes in the economics of Medicare drug coverage.
And all of that eventually lands in one place:
your plan.
The lesson for 2027 is simple:
Do not assume the Medicare plan you have today will be the Medicare plan you have next year.
Medicare Advantage Plans Are Under Pressure
Medicare Advantage continues to be enormously popular. More than half of eligible Medicare beneficiaries are enrolled in Medicare Advantage plans.
But popularity does not mean the plans will remain unchanged.
CMS finalized policies that are expected to increase Medicare Advantage payments by an average of 2.48% for 2027, representing more than $13 billion in additional payments to plans. When projected changes in risk scores are included, CMS estimates the increase at approximately 4.98%.
That sounds generous.
But insurers are also dealing with rising healthcare utilization and higher medical expenses.
Reuters reported earlier this year that insurers were expected to reduce some of the supplemental benefits Medicare Advantage members have become accustomed to, including dental, vision, and fitness benefits.
More recently, industry analysis has indicated that benefit reductions are indeed appearing in the 2027 market. Some large insurers are reducing or eliminating plans in selected areas as they try to improve profitability.
That does not mean Medicare Advantage is suddenly bad.
It means Medicare Advantage is becoming more local and more plan-specific.
A good plan in one county could be completely different from a plan carrying the same insurance company name 50 miles away.
Your $0 Premium Plan May Still Exist — But What Is Inside It?
One of the easiest Medicare mistakes is focusing on the monthly premium.
A plan may continue to advertise a $0 premium.
But that tells you almost nothing about what it will cost when you actually need healthcare.
For 2027, you need to look beyond the premium and ask:
- Did the hospital copayment change?
- Did specialist copays increase?
- Did the maximum out-of-pocket amount change?
- Are dental benefits smaller?
- Did the vision allowance change?
- Did the over-the-counter allowance disappear?
- Are your doctors still participating?
- Did your prescriptions move to a different drug tier?
That is why I keep saying:
Premium does not equal cost.
A $0-premium plan can still expose you to thousands of dollars of medical cost-sharing during a difficult healthcare year.
Part D Is Becoming One of the Biggest 2027 Stories
Prescription drug coverage deserves special attention this year.
CMS has announced that the temporary Part D Premium Stabilization Demonstration will end after 2026. The program was introduced to reduce premium volatility while the redesigned Part D benefit was being implemented.
Beginning in 2027, standalone Part D plans return to more traditional market pricing.
That does not automatically mean every premium will explode.
But it means seniors should pay particular attention to their Part D notices this fall.
CMS has already set the 2027 national base beneficiary premium at $41.33. That number is part of the formula used to calculate individual plan premiums; it is not necessarily what you personally will pay.
The final actual premiums vary by plan and location.
And there is another important change.
The annual out-of-pocket limit for covered Part D prescription drugs rises from $2,100 in 2026 to $2,400 in 2027.
That is a $300 increase in potential drug spending for people who reach the cap.
For someone taking inexpensive generics, that may not matter very much.
For someone taking expensive specialty medications, it could matter quite a bit.
Do Not Confuse the $2,400 Drug Cap With Your Total Medicare Costs
This deserves emphasis because it is frequently misunderstood.
The $2,400 Part D limit is not a limit on everything you spend for Medicare.
It applies to qualifying out-of-pocket spending for covered Part D drugs.
Your premiums do not simply disappear because you reached the drug cap.
And the cap does not protect you from medical cost-sharing under Medicare Advantage.
That means someone could simultaneously have:
a Part D premium,
drug expenses,
medical copayments,
and Medicare Advantage cost-sharing.
This is why looking at only one Medicare number can be misleading.
You need to look at your entire financial exposure.
Your Doctor May Matter More Than Your Premium
One of the most dangerous assumptions seniors make is:
“My doctor took the plan last year, so he must take it this year.”
Not necessarily.
Provider networks can change.
Hospitals can change contracts.
Doctors can leave networks.
Plans can leave markets.
CMS has specifically emphasized beneficiary protections relating to provider-network changes as part of its 2027 policies.
Before renewing a Medicare Advantage plan for 2027, verify your doctors and hospitals again.
Do not rely on what was true in 2026.
And whenever possible, verify with both the insurance company and the provider.
Star Ratings Are Changing Too
CMS is also changing the way Medicare Advantage and Part D plan quality is measured.
For the 2027 Star Ratings, CMS is removing a number of measures that it says provide little meaningful difference between plans and refocusing the system more heavily on clinical outcomes, patient experience, and quality of care.
That sounds technical, but there is a practical lesson.
A plan’s star rating is useful.
But it should never be the only reason you choose a Medicare plan.
A five-star plan that does not include your cardiologist is probably not the right plan for you.
A five-star plan that places your expensive medication on an unfavorable tier may not be the right plan either.
Quality ratings are part of the decision.
They are not the entire decision.
Medicare 2027 Is Becoming More About Risk
This may be the most important Medicare concept of all.
Choosing Medicare coverage is not simply about asking:
“Which plan has the lowest premium?”
The better question is:
“What financial risk am I accepting in exchange for that premium?”
With Medicare Advantage, you may have a lower monthly premium but accept more cost-sharing when you use healthcare.
With Medigap, you may pay significantly more every month but have much more predictable medical expenses.
Neither choice is automatically right.
The real issue is whether you understand the tradeoff.
Medicare is not just a medical decision.
It is a financial decision.
What Should You Do When Your 2027 ANOC Arrives?
Your Annual Notice of Change, commonly called the ANOC, may be one of the most important pieces of Medicare mail you receive all year.
Do not throw it away.
Do not glance at the first page and conclude that everything looks fine.
Compare 2027 with 2026.
Look specifically at your:
- Monthly premium
- Medical deductible
- Maximum out-of-pocket
- Specialist and hospital copayments
- Drug formulary and pharmacy network
Then verify your doctors.
If anything important changed, compare your alternatives.
October 15 Is When the Real Shopping Begins
The Medicare Annual Enrollment Period runs from October 15 through December 7.
But your homework should begin before October 15.
That means gathering:
your medications,
your preferred pharmacies,
your doctors,
your hospitals,
and your current plan information.
You cannot intelligently compare Medicare plans if you do not know what healthcare you actually use.
That is why our philosophy at MedicareSelfEnroll is:
Before You Compare Medicare Plans, Plan for Your Healthcare.
The 2027 Medicare Marketplace Is Still Taking Shape
CMS has said that the complete Medicare Advantage and Part D landscape, including final plan offerings and average premiums, will be released in mid-to-late September once offerings are finalized.
That is important because we are essentially standing at the starting line right now.
The broad policy changes are known.
The market pressures are becoming clear.
But the exact answer for an individual senior will depend on their ZIP code, prescriptions, doctors, hospitals, and available plans.
Anyone claiming right now that there is one universal “best Medicare plan for 2027” is selling you something.
There isn’t one.
The Bottom Line for Medicare 2027
The big Medicare story for 2027 may not be one dramatic new law.
It may be something far more practical:
the Medicare plan you already have could quietly become less valuable.
A premium could rise.
A benefit could shrink.
A doctor could leave.
A drug could change tiers.
A plan could disappear from your county altogether.
None of those changes necessarily means you should leave your current plan.
But they absolutely mean you should review it.
The worst Medicare strategy for 2027 may be the easiest one:
doing nothing simply because you did nothing last year.
At MedicareSelfEnroll.com, you can research and compare Medicare options at your own pace, without pressure.
Education First. Enrollment Second.
We Don’t Sell You Plans. We Help You Find the Right Choice.
And remember:
Before making any Medicare decision, you can also visit Medicare.gov, the official Medicare website.

William Vargas brings over 50 years of financial and insurance expertise to every Medicare conversation. He operates MedicareSelfEnroll.com, helping seniors in Florida, New York, and North Carolina — with no pressure, no phone calls required.