In This Article
- Your Plan Can Stay the Same Name and Still Change
- Medicare 2027 Is Giving You Choices
- Premium Is Not the Same as Cost
- Start With Your Doctors
- Then Check Your Prescriptions
- Look at the Maximum Out-of-Pocket Limit
- Do Not Get Distracted by the Extras
- Read Your Annual Notice of Change
- Five Questions to Ask Before Keeping Your Plan
- You Do Not Have to Change
- Medicare Shopping Has Changed
- AEP Ends December 7
Every fall, millions of people with Medicare face the same question:
Should I keep the Medicare plan I already have?
In an ordinary year, that may feel like an easy decision.
You like your plan.
Your premium looks reasonable.
Your doctors were covered last year.
Your prescriptions were covered last year.
So why change anything?
But 2027 deserves a closer look.
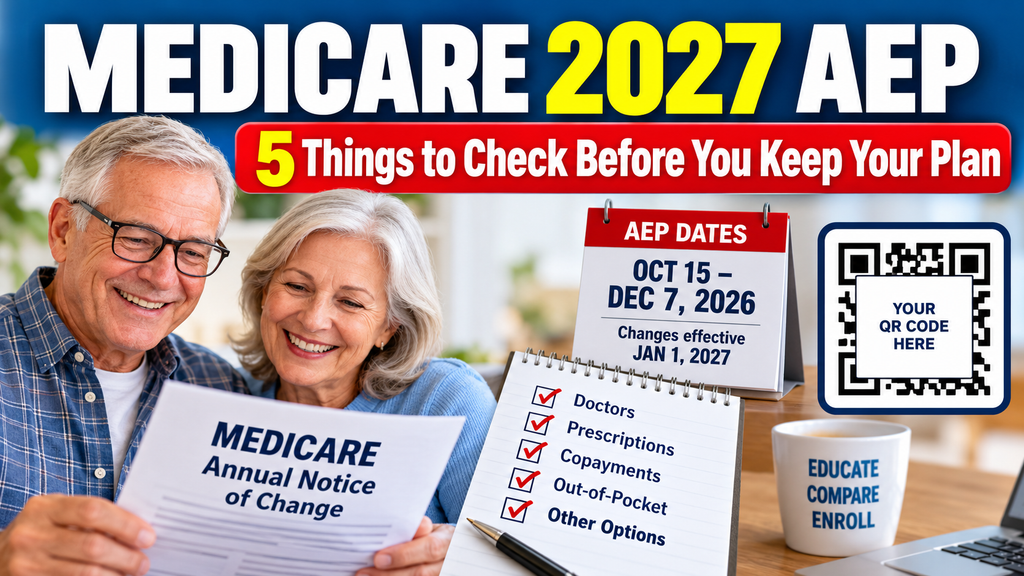
The Medicare Annual Enrollment Period is now underway, running from October 15 through December 7, 2026.
And this year, one of the most important things you can do may be surprisingly simple:
Do not assume your 2026 Medicare plan will work exactly the same way in 2027.
Your Plan Can Stay the Same Name and Still Change
This is where many people get caught.
A Medicare Advantage plan can keep the same familiar company name and still change important details from one year to the next.
The premium can change.
Copayments can change.
The maximum out-of-pocket limit can change.
Dental benefits can change.
Over-the-counter allowances can change.
Prescription drug coverage can change.
And perhaps most importantly, provider networks can change.
That means the question during AEP should not simply be:
“Do I like my plan?”
The better question is:
“Does my plan still work for me in 2027?”
Those are two very different questions.
Medicare 2027 Is Giving You Choices
There is some good news.
CMS projects that more than 99% of Medicare beneficiaries will have access to at least one Medicare Advantage plan in 2027, and about 97% will have access to 10 or more options.
CMS also projects the average Medicare Advantage monthly premium will decrease nationally in 2027.
That sounds encouraging.
But national averages do not tell you what is happening in your ZIP code.
And they certainly do not tell you whether your doctor accepts a particular plan.
That is why Medicare remains a local decision.
A plan that looks terrific in one county may be unavailable in another.
A plan with a low premium may have a network that does not include the doctors you want.
A plan with attractive extra benefits may have higher medical copayments.
And a zero-premium Medicare Advantage plan does not mean zero health care costs.
Premium Is Not the Same as Cost
This may be one of the most important Medicare lessons for 2027:
Premium does not equal cost.
Suppose Plan A has a $0 monthly premium.
Plan B costs $50 a month.
At first glance, Plan A looks cheaper.
But what happens when you actually use the plan?
What is the hospital copayment?
What does a specialist visit cost?
What is the copayment for diagnostic imaging?
What happens if you need outpatient surgery?
What is the maximum you could spend out of pocket during the year?
Suddenly that $0 premium does not tell you very much.
This is why shopping for Medicare based only on premium can be like buying a car based only on the price of the tires.
You have to look under the hood.
Start With Your Doctors
For many people, the most important part of a Medicare Advantage plan is not the dental allowance.
It is not the gym membership.
It is not the over-the-counter benefit.
It is your doctor.
Before changing plans, check your physicians.
That means more than asking whether “the medical group” accepts the insurance company.
Ask whether your individual physician participates in the specific Medicare Advantage plan you are considering for 2027.
Then check the specialists you regularly see.
Your cardiologist.
Your oncologist.
Your neurologist.
Your orthopedic doctor.
Your ophthalmologist.
Anyone important to your ongoing care.
And if you have a hospital you strongly prefer, check that too.
Provider directories can change, and networks can change from year to year.
A five-minute check today can prevent a very unpleasant surprise next year.
Then Check Your Prescriptions
Prescription drug coverage is another area that deserves an annual review.
Medicare Part D has gone through major changes in recent years, and additional provisions are being carried forward for 2027.
Your medications may remain the same while your plan’s formulary changes.
A drug might move to another tier.
The preferred pharmacy network may change.
Prior authorization rules may change.
Your expected annual prescription costs may change even if the plan premium barely moves.
That is why you should enter your actual medications into the Medicare Plan Finder rather than comparing plans based only on advertising.
The least expensive premium does not necessarily mean the lowest total prescription cost.
Look at the Maximum Out-of-Pocket Limit
If you are comparing Medicare Advantage plans, there is another number that deserves your attention:
The maximum out-of-pocket limit.
Think of this as part of your financial exposure if you have a difficult medical year.
Most of us do not expect to be hospitalized.
We do not expect surgery.
We do not expect cancer.
We do not expect a stroke.
But insurance is designed for what happens when life does not cooperate with our expectations.
Two plans that look very similar when you are healthy can look very different after a major medical event.
That is why Medicare is not simply a medical decision.
It is also a financial decision.
Do Not Get Distracted by the Extras
Dental.
Vision.
Hearing.
Transportation.
Over-the-counter allowances.
Fitness programs.
These benefits can certainly have value.
But they should not become the tail wagging the Medicare dog.
A $100 increase in an OTC allowance may sound attractive.
But not if your favorite specialist is no longer in network.
A generous dental benefit may sound appealing.
But not if the hospital system you use is outside the plan.
Look at the major medical coverage first.
Then look at the extras.
Read Your Annual Notice of Change
If you are already enrolled in a Medicare Advantage or Part D plan, your Annual Notice of Change is one of the most important documents you receive all year.
Do not throw it in the pile.
Do not assume it is just another insurance mailing.
It explains how your current coverage is changing for the following year.
Look for changes in:
Premiums
Deductibles
Copayments
Maximum out-of-pocket limits
Prescription drug coverage
Dental benefits
Vision benefits
Hearing benefits
Over-the-counter benefits
And other plan rules.
Then compare those changes with the alternatives available where you live.
Five Questions to Ask Before Keeping Your Plan
Before you decide to stay where you are for 2027, ask yourself five questions.
1. Are my doctors still in the plan?
Do not assume.
Verify.
2. Are my prescriptions still covered affordably?
Check the formulary and expected annual cost.
3. What changed in my copayments?
Pay particular attention to specialists, hospitals, imaging, outpatient procedures and other services you may actually use.
4. What is my maximum out-of-pocket exposure?
Know the number before you need the coverage.
5. Is there another plan that fits me better?
Not your neighbor.
Not the person on television.
Not the person sitting next to you at breakfast.
You.
Medicare is personal.
You Do Not Have to Change
This is important.
AEP is not about changing plans simply because you can.
Sometimes the best decision is to keep exactly what you have.
If your doctors remain in network, your prescriptions are covered, your costs are reasonable and the benefits fit your needs, staying put may be the right answer.
The goal is not to change.
The goal is to check.
There is a big difference.
Medicare Shopping Has Changed
For years, Medicare enrollment often meant calling an insurance agent, sitting through a sales presentation or responding to something you saw on television.
Today you have another option.
You can educate yourself first.
You can compare plans.
You can ask questions.
You can review your doctors and prescriptions.
And when you are comfortable with your decision, you can enroll online.
That is the idea behind MedicareSelfEnroll.com.
Learn.
Ask.
Compare.
Decide.
Enroll.
You can take your time.
You can review your choices.
And you can make the decision yourself.
No pressure.
No rush.
No need to make a decision simply because somebody is on the telephone trying to sell you something.
AEP Ends December 7
The Medicare Annual Enrollment Period runs from October 15 through December 7, 2026.
Changes made during this period generally take effect January 1, 2027.
Do not wait until December 7 at 10 o’clock at night to start checking your Medicare coverage.
Give yourself time.
Check your doctors.
Check your drugs.
Check your costs.
Compare the alternatives.
Then decide.
Because Medicare is changing.
The way you shop for Medicare should change also.
Before you enroll, educate yourself.
Visit MedicareSelfEnroll.com.
Ask questions.
Compare your choices.
And when you are ready, enroll with confidence.
Education first.
Enrollment second.

William Vargas brings over 50 years of financial and insurance expertise to every Medicare conversation. He operates MedicareSelfEnroll.com, helping seniors in Florida, New York, and North Carolina — with no pressure, no phone calls required.