In This Article
- Your Plan Has to Earn Your Business Again
- Start With Your Doctors
- Then Check Your Hospitals
- PPO Doesn’t Always Mean What People Think It Means
- Check Your Prescriptions Again
- Premium Does Not Equal Cost
- Know Your Maximum Out of Pocket
- Don’t Let the Extras Make the Decision
- Read Your Annual Notice of Change
- What If Your Current Plan Still Looks Good?
- Don’t Choose Medicare Like Your Neighbor
- Medicare Open Enrollment Is Decision Season
- A Better Way to Shop for Medicare
- The Bottom Line for Medicare 2027
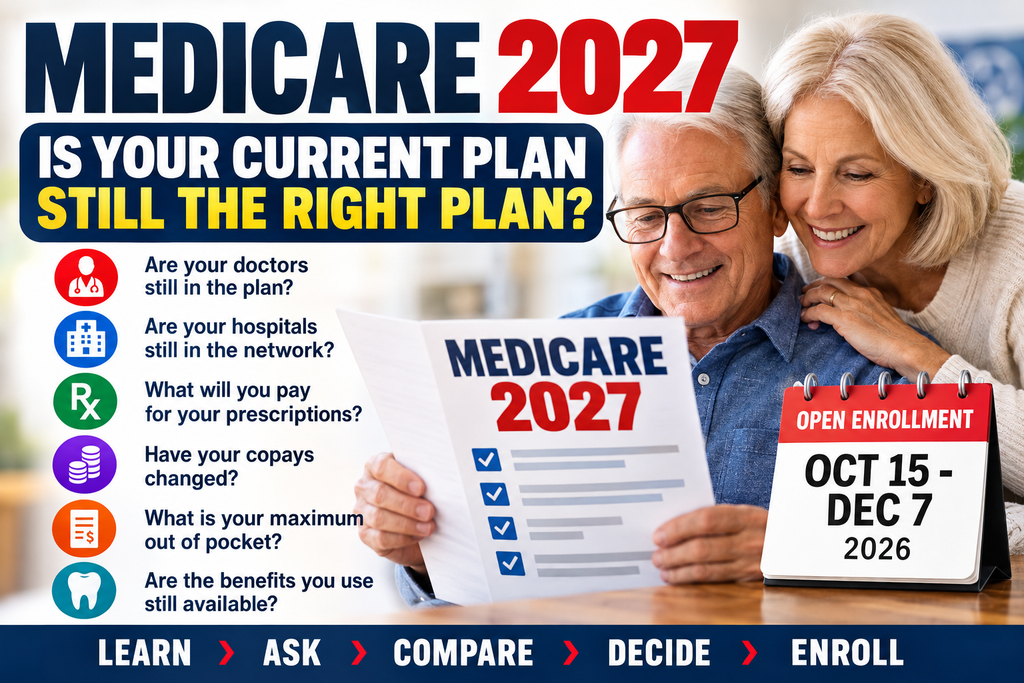
For millions of Americans with Medicare, October 15 marks the beginning of an important decision period.
Medicare Open Enrollment runs from October 15 through December 7, 2026. During this period, people with Medicare can review their current coverage and, if appropriate, make changes for 2027. Changes made during this period generally take effect January 1, 2027.
But there is an important point that sometimes gets lost in all the television commercials, postcards and phone calls.
You do not necessarily need a new Medicare plan.
What you need to determine is whether the plan you already have is still the right plan for you.
That is a very different question.
Your Plan Has to Earn Your Business Again
Think about how most people handle their Medicare coverage.
They enrolled in a Medicare Advantage plan several years ago.
They like their doctor.
The premium seems reasonable.
They haven’t had any major problems.
So when another Annual Enrollment Period arrives, they simply let the plan renew.
And sometimes that is exactly the right decision.
But Medicare plans can change from one year to the next.
Medicare specifically tells beneficiaries to review the Annual Notice of Change their plan sends each fall because it explains changes in costs, coverage and other plan features that will take effect in January.
In other words, don’t assume that because your plan worked well in 2026 it will work equally well in 2027.
Make your Medicare plan earn your business again.
Start With Your Doctors
For many people, this should be the first question.
Are my doctors still in the plan?
Notice that the question is not:
“Does my doctor take Medicare?”
A physician may accept Medicare but not participate in every Medicare Advantage plan.
If you have a Medicare Advantage plan, check your individual physicians against the 2027 plan network.
That includes your:
Primary care physician
Cardiologist
Oncologist
Orthopedist
Neurologist
Eye doctor
And any other specialist you see regularly.
If you rely on a large medical group, don’t simply assume every location or every physician within that group participates in the same plans.
Verify it.
And whenever possible, verify the actual doctor rather than relying solely on the name of the medical group.
Then Check Your Hospitals
This is one of the most overlooked parts of choosing a Medicare Advantage plan.
People spend a lot of time comparing dental allowances and over the counter benefits.
Then something serious happens and they discover that the hospital or health system they prefer is not participating in their plan.
Ask yourself:
If I needed surgery tomorrow, where would I want to go?
Then check whether that hospital participates in the plan you are considering.
For people who routinely travel between counties for medical care, this becomes even more important.
Your healthcare world may be much larger than your ZIP code.
PPO Doesn’t Always Mean What People Think It Means
Many people see the letters PPO and immediately think:
“I can go anywhere.”
Not quite.
A PPO generally gives you more flexibility than an HMO to receive care outside the plan’s network.
But that doesn’t mean your cost will be the same.
An out of network service might have a percentage coinsurance instead of a simple fixed copayment.
That difference can become significant with expensive medical treatment.
So when comparing PPO plans, don’t stop at:
“Does it have out of network coverage?”
Ask:
“How much will I pay if I actually use it?”
That is the number that matters.
Check Your Prescriptions Again
Prescription coverage deserves its own review every year.
A drug that was affordable this year might be handled differently next year.
The medication could change tiers.
Your preferred pharmacy could have different pricing.
The plan’s formulary could change.
Or another available plan might handle your particular combination of medications differently.
So don’t simply ask whether your medications are covered.
Ask:
What will I actually pay for my prescriptions in 2027?
And enter every medication you take when comparing plans.
The cheapest plan for your neighbor may not be the cheapest plan for you because you don’t necessarily take the same medications.
Premium Does Not Equal Cost
This may be one of the most important lessons in Medicare.
A low premium does not necessarily mean a low cost.
A zero dollar Medicare Advantage premium can be attractive.
But the premium is only one number.
You also have to look at:
Doctor copayments
Specialist copayments
Hospital costs
Diagnostic imaging
Outpatient surgery
Emergency room costs
Prescription expenses
Out of network costs
And the plan’s maximum out of pocket.
These numbers tell you much more about your financial exposure than the premium alone.
This is particularly important for someone with chronic medical conditions or someone who anticipates surgery or significant medical care during the coming year.
Know Your Maximum Out of Pocket
Most of us buy insurance hoping we won’t have to use very much of it.
That’s good.
But insurance is really there for the bad year.
Suppose you are healthy today.
Then suddenly you need surgery.
Or chemotherapy.
Or rehabilitation.
Or repeated specialist visits and diagnostic testing.
That is when the structure of your health plan becomes much more important.
Look at the plan’s maximum out of pocket amount for covered Medicare Part A and Part B services.
Hopefully you will never reach it.
But you should know what the number is.
Think of it as part of the financial risk you’re accepting when you choose a plan.
Don’t Let the Extras Make the Decision
Dental benefits are useful.
So are vision benefits.
Hearing aid benefits can be valuable.
Over the counter allowances can certainly help.
Some plans offer transportation, fitness programs or Part B premium reductions.
There is nothing wrong with considering those benefits.
But they should not come before your medical coverage.
If one plan gives you another few hundred dollars of dental benefits but your preferred hospital isn’t in the network, ask yourself which one matters more.
Your toothpaste should probably not choose your health insurance.
Read Your Annual Notice of Change
Every fall, Medicare plans send members an Annual Notice of Change, commonly called the ANOC.
Don’t throw it into the pile of Medicare advertising.
This is one document you should actually read.
Medicare says the ANOC explains changes in coverage, costs and other plan details that become effective in January.
Look specifically for changes involving:
Premiums
Copayments
Maximum out of pocket limits
Prescription coverage
Dental benefits
Vision benefits
Hearing benefits
Over the counter benefits
Provider networks
And any other benefits you regularly use.
Even one meaningful change might justify comparing your alternatives.
What If Your Current Plan Still Looks Good?
Then keep it.
There is no prize for changing Medicare plans every year.
Medicare says that if you keep your current Medicare health and drug coverage, you generally don’t need to take action and the coverage continues automatically, subject to the plan continuing and any new year’s changes.
Sometimes the smartest Medicare decision is doing absolutely nothing.
But there is a difference between doing nothing because you reviewed your coverage and decided it remains the best choice…
and doing nothing because you never looked.
That’s why I say:
Make your plan earn your business again.
Don’t Choose Medicare Like Your Neighbor
Here’s another mistake I see frequently.
“My neighbor has that plan and loves it.”
That’s nice.
But your neighbor may have different doctors.
Different prescriptions.
Different hospitals.
Different medical conditions.
Different travel habits.
And different financial priorities.
There is no universally “best” Medicare plan.
There is only the plan that best fits your circumstances.
Medicare Open Enrollment Is Decision Season
Medicare’s annual Open Enrollment Period runs from October 15 through December 7. During that period, people can make certain changes involving Medicare Advantage plans and Medicare drug coverage, with new coverage generally beginning January 1.
That doesn’t mean you should wait until December 6.
Start reviewing now.
Take your time.
Ask questions.
Compare carefully.
Check your doctors.
Check your hospitals.
Check your prescriptions.
Check the costs.
And then make your decision.
A Better Way to Shop for Medicare
For years, Medicare shopping has often worked backward.
Someone calls you.
They start talking about a plan.
Then they try to convince you to enroll.
I think seniors deserve a different approach.
Learn first.
Ask questions.
Compare your choices.
Decide what works for you.
Then enroll.
Education first.
Enrollment second.
That philosophy becomes even more important as Medicare choices become more complicated.
You don’t need someone telling you which television commercial has the best benefits.
You need good information.
And you need enough time to make your own decision.
The Bottom Line for Medicare 2027
Before you automatically renew your Medicare plan for another year, ask one question:
Is this still the right plan for me?
If the answer is yes, wonderful.
Keep it.
If the answer is no, investigate your alternatives.
But don’t make your decision based solely on a premium, a dental allowance or a television advertisement.
Look at the whole plan.
Doctors.
Hospitals.
Prescriptions.
Copayments.
Maximum out of pocket.
Travel needs.
And the benefits you actually use.
Because Medicare is changing.
And the way you shop for Medicare should change also.
Educate yourself first.
Compare your choices.
Then decide.
An informed senior makes better choices.

William Vargas brings over 50 years of financial and insurance expertise to every Medicare conversation. He operates MedicareSelfEnroll.com, helping seniors in Florida, New York, and North Carolina — with no pressure, no phone calls required.