In This Article
- Medicare Advantage Premiums Are Expected to Fall
- Your Doctor May Matter More Than Your Premium
- PPO Does Not Always Mean What People Think
- Look Beyond the Premium
- Prescription Drugs Need Their Own Review
- Benefits Can Change Too
- What If Your Medicare Plan Is Ending?
- Your 2027 Medicare Checklist
- Medicare Is Local
- The Annual Enrollment Period Begins October 15
- Medicare Shopping Is Changing
- The Bottom Line for Medicare 2027
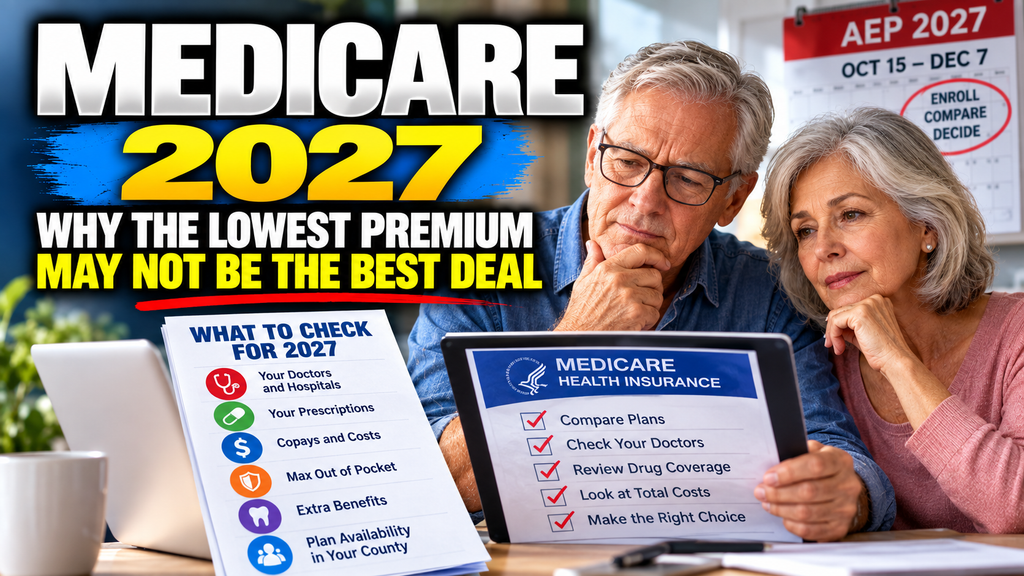
When Medicare beneficiaries begin looking at their choices for 2027, one number will probably receive more attention than almost anything else:
The monthly premium.
That is understandable.
Nobody wants to pay more than necessary for health insurance.
But Medicare in 2027 is providing a very important reminder:
Premium does not equal cost.
A Medicare Advantage plan with a zero dollar premium could potentially cost you considerably more during the year than another plan with a monthly premium.
At the same time, a more expensive plan is not automatically better.
The only way to know is to look underneath the premium and examine how the plan actually works for you.
That means reviewing your doctors, hospitals, prescriptions, copayments, maximum out of pocket exposure and benefits.
For 2027, that review may be more important than ever.
Medicare Advantage Premiums Are Expected to Fall
There is some genuinely good news.
The Centers for Medicare and Medicaid Services projects that the weighted average monthly Medicare Advantage premium will decline from $14.37 in 2026 to approximately $12 in 2027.
That represents a decrease of about 16.5 percent.
CMS also reports that more than 99 percent of Medicare beneficiaries should have access to at least one Medicare Advantage plan in 2027, and 97 percent should have access to ten or more choices.
Those national numbers sound encouraging.
But there is another side to the story.
Insurance companies are making significant changes to where they offer plans and how some of those plans operate.
UnitedHealthcare, Aetna and other insurers have indicated that some 2027 offerings will use more limited provider networks. Some insurers are also reducing their presence in selected counties or shifting emphasis between PPO and HMO plans.
That means a plan can have a very attractive premium while offering a very different network than the plan you had before.
This is why we continually emphasize at MedicareSelfEnroll.com:
Education first. Enrollment second.
Your Doctor May Matter More Than Your Premium
Imagine that you find a Medicare Advantage plan costing zero dollars per month.
Sounds wonderful.
Then you discover that the cardiologist you have seen for eight years is not participating.
Or your preferred hospital is outside the network.
Or the specialist you need requires different authorization rules.
Suddenly that zero dollar premium does not look quite as attractive.
Provider networks are becoming one of the most important issues to examine for 2027.
Do not simply ask:
“Does my doctor accept Medicare?”
That is not enough.
For Medicare Advantage, the important question is:
“Does my doctor participate in this specific Medicare Advantage plan for 2027?”
Those are two very different questions.
Medicare Advantage plans contract with individual doctors, hospitals and medical groups. Networks can change from one year to the next.
A doctor who participated in your plan during 2026 may not necessarily participate in the same plan during 2027.
Before enrolling, verify your important doctors directly with the plan and, when possible, with the provider’s office.
PPO Does Not Always Mean What People Think
Many Medicare beneficiaries prefer PPO plans because they generally provide some ability to receive care outside the network.
But PPO does not mean every doctor is automatically available to you at the same cost.
Out of network services may have higher copayments or coinsurance.
Some providers may not agree to see the plan’s members.
And insurers have been reconsidering PPO availability in some markets because PPO plans are typically more expensive to operate.
That makes it important to examine the actual provider network rather than simply seeing the letters PPO and assuming everything is covered everywhere.
Similarly, an HMO may work very well for someone whose doctors and hospitals are all comfortably inside the network.
There is no universally correct answer.
The right question is:
Does this plan work for me?
Look Beyond the Premium
When comparing Medicare plans for 2027, there are several numbers that deserve your attention.
The premium is only one of them.
Look at your primary care copayment.
Look at specialist copayments.
Look at hospital costs.
Look at diagnostic testing.
Look at outpatient surgery.
Look at ambulance costs.
Look at rehabilitation.
Then look at one of the most important numbers on the entire Summary of Benefits:
The maximum out of pocket limit.
That number represents the maximum amount you could be responsible for paying for covered Part A and Part B services under the plan during the year, subject to the plan’s rules.
Many people never come close to reaching that amount.
Hopefully you never will.
But insurance exists for the years when things do not go according to plan.
A hospitalization, cancer diagnosis, stroke, major surgery or serious illness can make the maximum out of pocket number suddenly much more important than the monthly premium.
This is why we use a simple principle:
Do not shop Medicare by premium alone.
Prescription Drugs Need Their Own Review
Prescription coverage deserves a separate analysis.
Your medical benefits can remain relatively attractive while your prescription costs change substantially.
A medication can move to another tier.
A plan can change its formulary.
A preferred pharmacy arrangement can change.
Prior authorization or quantity limits may apply.
And your own prescriptions may change during the year.
For 2027, CMS has set the standard Part D deductible at $700 and the annual out of pocket threshold for covered Part D medications at $2,400.
Once qualifying out of pocket spending reaches the catastrophic threshold, beneficiaries pay no additional cost sharing for covered Part D drugs for the remainder of the year.
That $2,400 figure is an important financial protection, but it does not mean everyone will spend $2,400.
Your actual prescription costs depend upon the medications you take and your specific plan.
Medicare beneficiaries can compare prescription drug plans and enter their medications using Medicare.gov.
Do not choose a drug plan simply because its premium is inexpensive.
A low premium plan that handles your prescriptions poorly can be far more expensive than a higher premium plan that covers them favorably.
Benefits Can Change Too
One reason Medicare Advantage became popular was the additional benefits many plans offered.
Depending upon the plan and location, those benefits can include dental, vision, hearing, fitness programs, transportation, over the counter allowances and other supplemental benefits.
But these benefits are not guaranteed to remain identical every year.
An allowance can become smaller.
A copayment can increase.
Dental benefits can change.
A giveback can disappear.
Transportation rules can change.
The number of covered visits can change.
That is why beneficiaries receive an Annual Notice of Change, commonly called the ANOC.
Do not throw it into the pile with the advertisements.
Open it.
The ANOC tells you what is changing in your current plan for the following year.
Think of it as your Medicare plan saying:
“Here is what will be different January 1.”
Those differences deserve your attention.
What If Your Medicare Plan Is Ending?
Some beneficiaries will face a bigger change.
Their current Medicare Advantage plan may no longer be available in their county for 2027.
This does not mean they are losing Medicare.
It means that particular private Medicare plan is no longer available to them.
That distinction is important.
If your plan is not renewing, read every notice the insurance company sends you.
You may have enrollment options and, depending upon your circumstances, additional rights that someone whose plan continues would not have.
Do not assume that you simply need to pick whatever replacement plan appears most similar.
Use the change as an opportunity to examine all of your choices.
Your 2027 Medicare Checklist
Before deciding to keep or change your Medicare plan, answer these questions:
Are my important doctors still participating?
Is my preferred hospital still available?
Are my prescriptions still covered?
Did any medications change tiers?
What are my specialist copayments?
What does hospitalization cost?
What is my maximum out of pocket exposure?
Did my dental, vision, hearing or over the counter benefits change?
Did my premium change?
Are there better alternatives available in my county?
Notice where premium appears on that list.
It matters.
But it is only one part of the decision.
Medicare Is Local
One of the biggest mistakes people make is watching a national television commercial and assuming that the advertised plan is available to them.
Medicare Advantage is local.
Plan availability can vary from one county to another.
A company can have an excellent plan in one county and a completely different offering in the county next door.
That is why someone living in New York may have choices completely different from someone living in Florida, North Carolina or Texas.
Even neighboring counties can have different plans.
National statistics are useful for understanding trends.
But your Medicare decision needs to be based upon what is actually available where you live.
The Annual Enrollment Period Begins October 15
Medicare’s Annual Enrollment Period for 2027 coverage runs from October 15 through December 7, 2026.
Changes made during this period generally take effect January 1, 2027.
CMS specifically encourages Medicare beneficiaries to use Open Enrollment to review their coverage and compare their choices.
That advice is especially appropriate this year.
Even if you are perfectly happy with your current plan, spend a few minutes reviewing it.
You may decide to keep it.
There is absolutely nothing wrong with that.
Changing plans simply because another plan exists is not a strategy.
But keeping a plan simply because you had it last year is not a strategy either.
Medicare Shopping Is Changing
For many years, Medicare shopping often meant sitting across the kitchen table from an insurance salesperson and listening to a presentation.
Technology has changed that.
Today seniors can educate themselves, research their options, ask questions and compare Medicare plans online.
At MedicareSelfEnroll.com, our approach is simple:
Learn. Ask. Compare. Decide. Enroll.
You can take your time.
Ask questions.
Compare your choices.
And make your own decision.
Because an informed senior usually makes a better Medicare decision than someone who simply responds to the loudest advertisement.
The Bottom Line for Medicare 2027
The Medicare story for 2027 cannot be summarized by saying premiums are going up or premiums are going down.
The real story is more complicated.
Average Medicare Advantage premiums are projected to decline nationally.
Prescription drug protections continue to evolve.
At the same time, insurance companies are adjusting networks, service areas and plan designs.
Some beneficiaries will have excellent options.
Others may find that the plan they relied upon is changing significantly or disappearing altogether.
That is why 2027 should be the year you stop asking only:
“What does this plan cost per month?”
Instead ask:
“What could this plan cost me if I actually need healthcare?”
Then ask:
“Are my doctors there?”
“Are my prescriptions covered?”
“What happens if I get sick?”
Those questions tell you much more about a Medicare plan than the premium printed at the top of the brochure.
Medicare is changing.
The way you shop for Medicare should change also.
Before you enroll, educate yourself.
Visit MedicareSelfEnroll.com to learn about Medicare, compare available plans and make your decision with confidence.
Education first. Enrollment second.

William Vargas brings over 50 years of financial and insurance expertise to every Medicare conversation. He operates MedicareSelfEnroll.com, helping seniors in Florida, New York, and North Carolina — with no pressure, no phone calls required.